Actual cash value
ACV accounts for depreciation. The payment can leave a difference between the settlement and the cost of a new roof.
Understand roof coverage, depreciation and payment stages before placing them beside the work.
Free roof inspections. Clear repair and replacement options.
The policy and the cause of loss determine coverage. An old roof or a repair price above a deductible does not, by itself, establish an insured claim. Understanding payment terms helps put the roofing scope beside what the policy provides.
Roof settlement can differ from the coverage on the rest of the house.
ACV accounts for depreciation. The payment can leave a difference between the settlement and the cost of a new roof.
Replacement-cost coverage addresses equivalent replacement under its policy terms. Depreciation can be withheld initially and released after qualifying completed work.
The applicable deductible, exclusions, endorsements and covered work determine the owner’s part of the cost.
Coverage definitions: Missouri Department of Insurance roof coverage guidance. Checked November 2, 2026.
Keep clear of unsafe areas. Describe active water entry when requesting help; temporary protection and permanent repair have different scopes.
The roof assessment identifies current condition. The insurer determines coverage under the policy, and a nearby storm record alone does not establish property damage.
Newly discovered damage can require an additional scope and insurer review. Policy deadlines and requirements govern replacement-cost recovery.
Payment stages and supplemental work: Missouri consumer claims guidance. Checked November 2, 2026.
The free inspection can examine damage, the surrounding material and what a repair or replacement would physically involve. That roofing answer is useful whether the work is paid privately or considered in a claim.
Ordinary wear and a covered event are different causes. Coverage and any payment follow the policy and insurer’s actual decision, while the roofing work needs a sound scope and compatible materials.
Explore storm roof assessment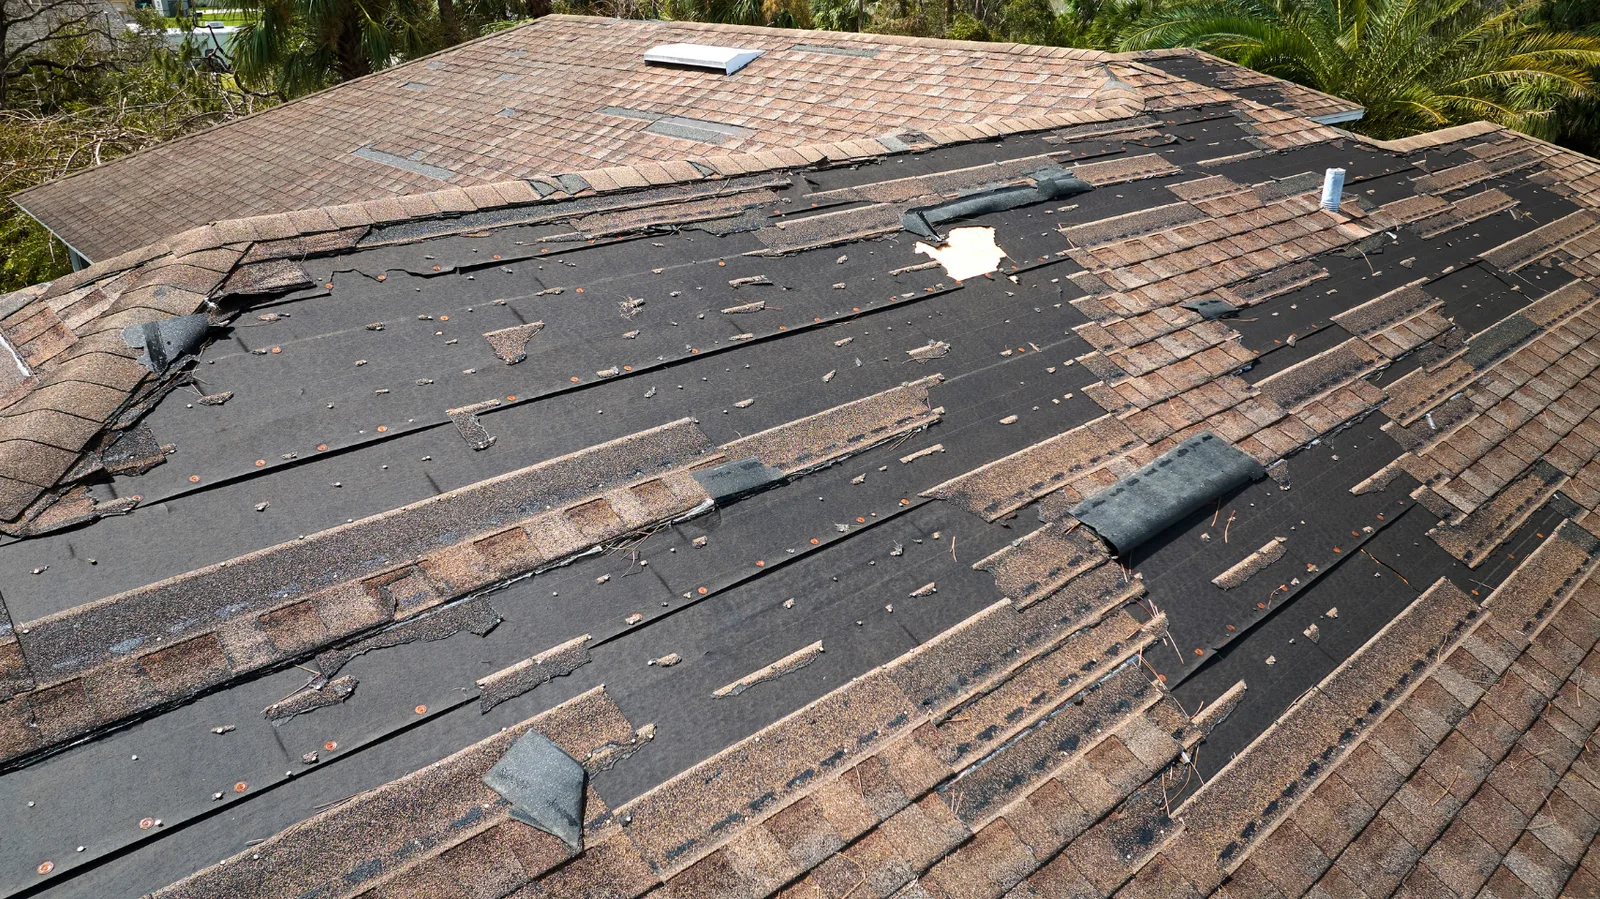
Ordinary wear is not the same as damage from a covered event. The policy, endorsements and actual cause determine what is covered.
Not necessarily. Deductibles, depreciation and payment terms can affect the first payment and any later recovery. The policy requirements control.
Tell us what changed and request a free roof inspection. We can discuss the actual roofing scope.
(816) 330-2235